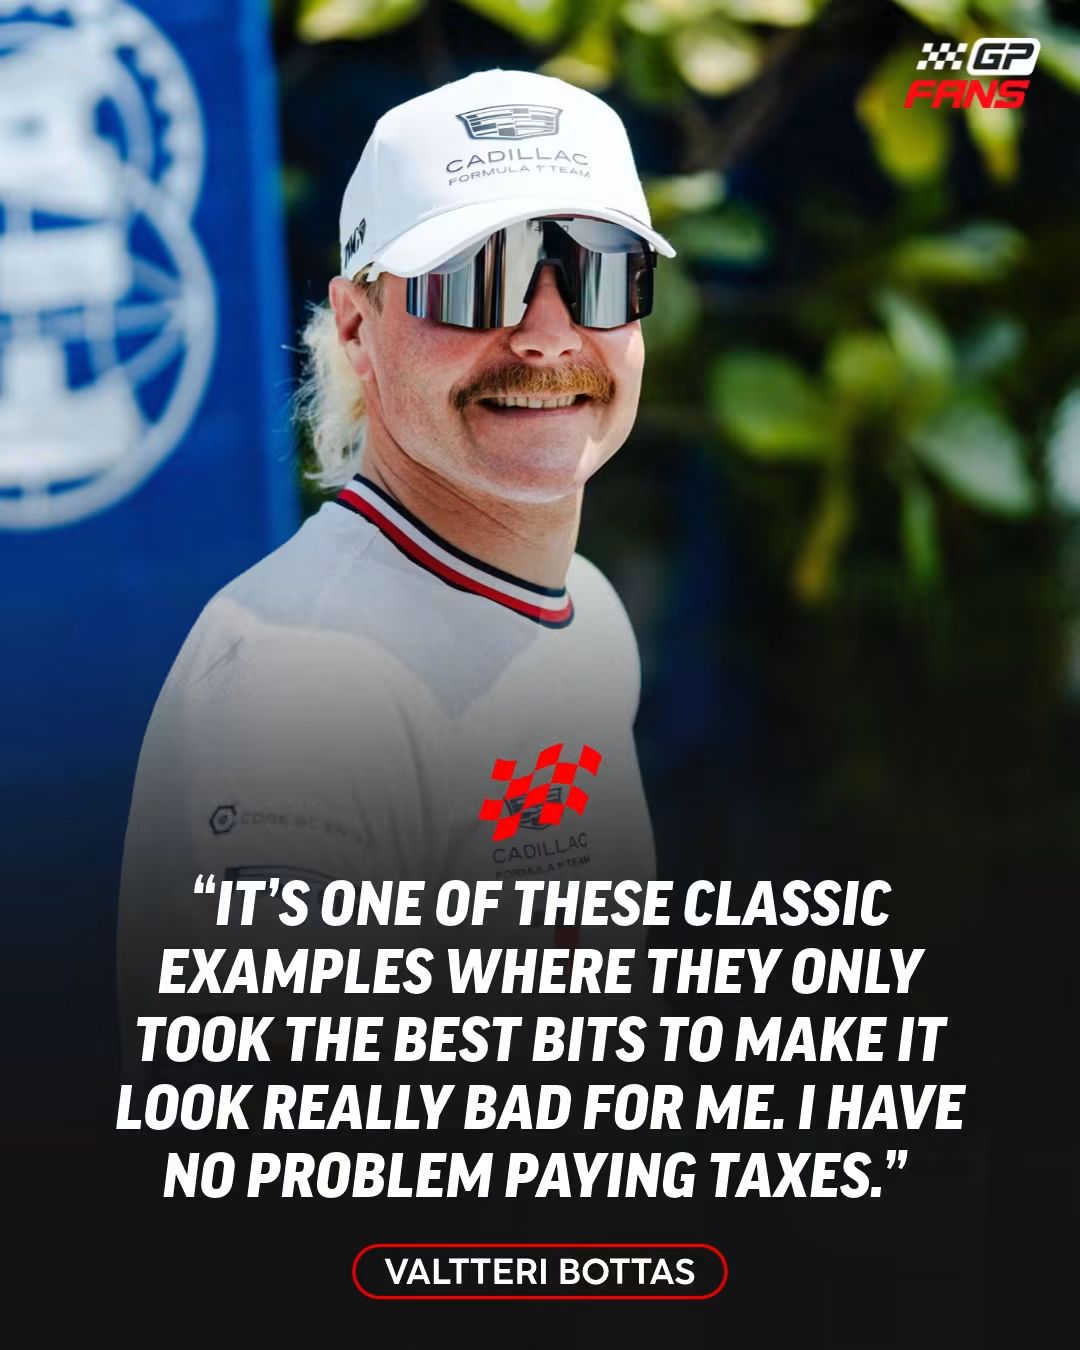
VALTTERI BOTTAS HAS NO PROBLEM PAYING TAXES — BUT THE ITALIAN BACK-TAX SHOCK STILL FRUSTRATES THE F1 PADDOCK
Valtteri Bottas lives in Monaco. Like a large share of the Formula 1 grid, the Finnish driver has long based himself in the Principality for its well-known combination of lifestyle, privacy, location, and zero personal income tax on non-French residents. That residency status has never stopped him from stating a simple principle: he has no problem paying taxes.
In early October 2026 comments that cut through calendar speculation, Bottas made the point explicitly while addressing the possibility of an Italian season finale. The context was not abstract fiscal philosophy. Italian authorities had recently recovered a substantial sum — reports put the figure near €100 million — in back taxes and related payments linked to Formula 1 activity on Italian soil over the previous seven or eight years. Drivers and teams faced retrospective bills after years in which many had been told they did not need to file certain returns in Italy.
Bottas’s clarification was clear. Paying tax is not the issue. The frustration comes from the sudden, multi-year look-back and the lack of earlier clarity.
WHY SO MANY F1 DRIVERS CHOOSE MONACO IN THE FIRST PLACE
Monaco’s appeal to elite drivers is structural. No personal income tax, no wealth tax, and no capital gains tax for qualifying residents create a clear financial difference on multi-million salaries, bonuses, and endorsement income. Add proximity to major European hubs, high security, relative privacy among other high-net-worth residents, and a climate that suits year-round training, and the Principality becomes a logical base. Bottas has maintained a Monaco residence for years alongside other properties.
This arrangement does not eliminate tax obligations elsewhere. Drivers still face source-country rules when they race. In many jurisdictions a portion of race-related earnings is taxed locally. Italy’s enforcement action highlighted how those rules can be applied retroactively when authorities decide previous practice fell short. The result was large collective payments and a lasting sense among some drivers that the process lacked predictability.
THE ITALIAN TAX EPISODE AND ITS PRACTICAL IMPACT
The core of the dispute involved the classification of foreign drivers as independent contractors generating income during Italian Grands Prix. Teams had not consistently withheld and remitted the expected amounts over several seasons that included Monza, Imola, and earlier events. When the Guardia di Finanza and tax authorities reviewed the period, the bills arrived. Drivers and teams settled. Bottas and others emphasized that the objection was never to the principle of taxation itself. It was the retrospective nature of the claims and the earlier understanding that filing was unnecessary.
That experience now colors views of additional Italian races. When calendar uncertainty arose around the 2026 season finale — linked to broader geopolitical considerations affecting Middle Eastern events — Bottas openly stated that many drivers were unenthusiastic about a late-season Imola date. Weather (fog, early sunsets, lower temperatures) featured in the comments, but the recent tax episode was also cited as a reason drivers would prefer alternatives. Abu Dhabi, by contrast, was noted for the absence of equivalent local tax friction on race earnings.
Max Verstappen offered a contrasting, characteristically direct view: there is no tax problem if you simply pay what is owed. The exchange illustrated different personal tolerances for fiscal uncertainty rather than any fundamental disagreement on legality.
WHAT THIS MEANS FOR DRIVERS, TEAMS, AND THE SPORT
For individual drivers the financial hit is real even at their earning levels. A sudden multi-year bill affects cash flow, planning, and the net value of contracts already negotiated under different assumptions. For teams the administrative and cash burdens compound across multiple drivers and seasons. For Formula 1 as a commercial enterprise the episode raises questions about consistency of host-country tax treatment. Race organizers and promoters compete for calendar slots; unpredictable or retrospective tax enforcement can become another factor in those negotiations alongside fees, infrastructure, and logistics.
The broader industry implication is straightforward. Formula 1 operates as a global traveling circus with highly mobile, high-earning talent. Host nations that provide clear, advance guidance on tax treatment for non-resident athletes reduce friction. Those that apply rules retroactively create hesitation. Monaco residency solves the home-base tax question for many drivers but does nothing to insulate them from source taxation at each race. Clarity remains the practical requirement.
LOOKING AHEAD: PREDICTABILITY AS A COMPETITIVE FACTOR
Future calendar decisions will continue to balance sporting, commercial, and geopolitical realities. Drivers will keep preferring venues where the fiscal rules are known in advance. Teams will factor potential tax exposure into overall cost modeling. Promoters in high-tax jurisdictions may need to demonstrate transparent frameworks if they want to remain attractive for late-season or replacement events.
Bottas’s position is consistent with both his Monaco base and his public comments. He accepts the obligation to pay tax where it is due. He objects to being told one set of rules for years and then facing a substantial multi-year adjustment. That distinction matters. It separates legitimate tax planning and residency choices from resistance to lawful obligations.
In a sport defined by precision, the same preference for known parameters applies off the track. Drivers will race wherever the championship requires. They will prefer to know the full cost of doing so before the lights go out.